

Borrow Money Instantly - Fundi
by Sunny Pal Singh Gill
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
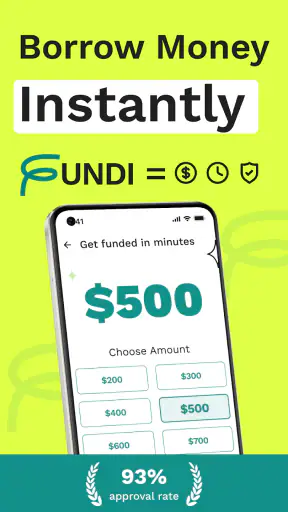
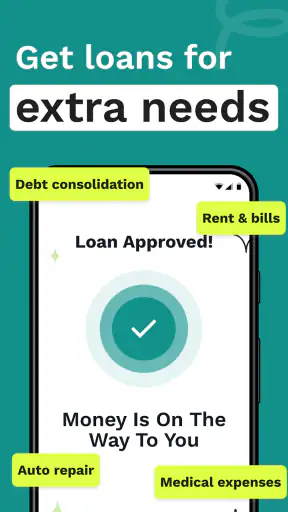
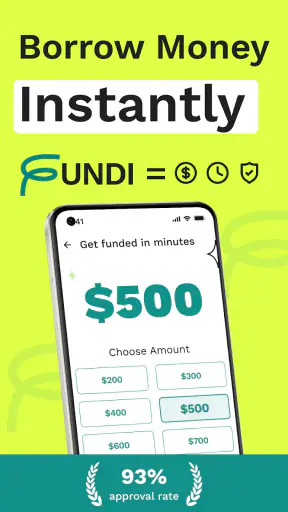
 Analysis by Getfullapps
When money gets tight between paydays, the temptation is to choose the first cash-advance app that promises a quick answer. I looked at Borrow Money Instantly - Fundi with that exact situation in mind, but also from a household perspective: what happens when a finance app is used on a shared phone, discussed between partners, or opened by someone who is not the person responsible for repayment? My impression is that this is a focused borrowing tool rather than a complete money-management app. It may suit an adult who needs to explore an urgent loan option, but it deserves more caution than its simple name suggests.
The app is free to install and sits in the finance category. It was developed by Sunny Pal Singh Gill, and its public reception is strong, with a 4.7 average from around 32 thousand ratings and roughly 1.9 thousand written reviews. It has passed the half-million-install mark, which suggests that many people have at least tried it. Those figures are useful context, but they should not be confused with a guarantee that every borrower will receive the same result. A loan app can be popular and still be unsuitable for a particular household budget.
How Fundi fits into a shared household money decision
A realistic example is a couple dealing with an unexpected repair just before payday. One person may install the app because they are handling the immediate payment, while the other wants to understand the repayment burden before agreeing. In that situation, Fundi can be a starting point for a conversation, not a substitute for one. I would avoid treating the presence of the app on one phone as permission for both people to borrow or make decisions on behalf of the other.
The most important practical boundary is simple: the person whose identity and financial information are used should be the person making the application. A shared device can make this unclear, especially if both partners use the same phone or if a family member regularly borrows it. Before opening the application, I would decide whose account, phone number, email address and financial details are being used, then keep the process with that person from beginning to end.
This matters because an instant-loan workflow is not like checking a household shopping list. It can involve personal information, eligibility questions and repayment responsibilities. Even when two adults share expenses, they do not automatically share the same borrowing history or obligations. I would never enter another person’s details simply because they are a spouse, parent or roommate, and I would not leave a partially completed application open on a shared screen.
Fundi’s free installation lowers the barrier to trying it, which is convenient when someone needs to investigate an option quickly. It also makes restraint important. “Free” describes access to the app, not the overall cost of borrowing. Before accepting anything, I would read every displayed repayment figure, fee, due date and condition carefully. If the final amount is difficult to understand, I would stop and compare it with a bank, credit union or another established lending option.
Setting boundaries before anyone taps through the application
My preferred household setup is to use the app privately on the borrower’s own device or user profile. I would turn off casual sharing of the screen, close the app after use and avoid saving sensitive information where another household member can see it. These are not special Fundi features; they are sensible habits for any finance application, particularly one intended for borrowing.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
If a shared phone is unavoidable, I would first tell the other users that a loan application is being considered and agree on who is responsible for the next steps. I would also make sure notifications are not being mistaken for approval, repayment confirmation or a completed loan. A message that encourages someone to return to the app is not the same as a clear understanding of the financial agreement.
There is another useful boundary that is easy to miss: separate research from commitment. I would open Fundi to learn what information it requests and what options appear, but I would not rush from the first screen to acceptance simply because the household is under pressure. Taking a screenshot of a quoted figure may help with comparison, provided it does not expose private information, but the final terms should always be reviewed in the app at the point of decision.
I would also keep a written household note showing who is considering the loan, why it is needed and how repayment would fit into the next budget. That small step prevents a common problem: one person assumes the other has checked the cost, while neither has done so. The app can help begin the process, but it cannot replace a shared agreement about affordability.
Coordinating repayment without turning the phone into a family account
For a couple, coordination should focus on the repayment plan rather than on sharing login details. One person can be the borrower while both people review the household budget together. I would avoid passing passwords around or leaving an account signed in for convenience. The goal is transparency between adults, not a single informal account that everyone can open.
A useful workflow is to write down the expected repayment date, the amount that must remain available and the household bills that take priority. Then compare that plan with actual income timing. A fast approval may solve a short-term timing problem, but it can create a second problem if the repayment lands before the household has recovered. This is where a slower alternative may be better, even if it feels less convenient.
Fundi is most appealing when the need is genuinely urgent and the borrower already knows exactly how the repayment will be handled. It is less attractive when the app is being used to cover an ongoing monthly shortfall. Repeatedly borrowing for groceries, utilities or existing debt can hide a structural budget problem. In that case, I would rather see the household contact creditors, review recurring expenses or seek free financial guidance than make another quick application.
Shared-device use also raises a coordination issue around notifications. If other people can see messages on the lock screen, private financial information may be exposed. I would review the phone’s notification settings before using any borrowing service and close the session when finished. Again, this is a device-level precaution rather than a feature I would attribute to Fundi, but it is especially relevant when several people use one handset.
The app should not become a shortcut for asking a partner to approve a loan after the application has already been submitted. A better approach is to agree on a maximum household repayment before applying. If the displayed terms exceed that limit, the answer should be no, even if the approval appears fast. This is one of the strongest reasons to involve another trusted adult before commitment rather than after it.
Age, trust and the meaning of an Everyone rating
Fundi carries an Everyone content rating, and its minimum operating requirement is Android 5.0. That makes the app broadly accessible from a device-compatibility and content-rating perspective, but borrowing is still an adult financial decision. An age label should not be read as an invitation for children to apply, experiment with loan forms or handle a parent’s financial details.
If a teenager uses the same phone, I would keep the app out of casual reach and explain plainly that tapping through a finance application is not harmless browsing. Younger household members may understand that money is involved without understanding identity checks, repayment obligations or the consequences of missed payments. The responsible adult should control the application and explain the decision in age-appropriate language.
Trust matters between adults too. I would not recommend installing Fundi on a partner’s phone without telling them, using someone else’s device to submit information, or assuming that shared household finances mean shared authority to borrow. A finance app should be treated more like a bank document than like a shared entertainment app.
The developer name, Sunny Pal Singh Gill, is visible as part of the app’s identity, and the current version is 1.0.6. I would check that the app is installed from the legitimate store listing and that the developer information matches before entering anything sensitive. I would also keep the app updated through the normal store process. Those checks do not prove that a loan is suitable, but they reduce the chance of confusing the intended application with an imitation.
One question many people have is whether a quick-approval promise means approval is automatic. I would not assume that. The store summary presents instant loans and fast approval as the central purpose, but an individual result can still depend on the application process and the borrower’s circumstances. The sensible approach is to treat the app as a way to request or explore borrowing, not as guaranteed access to money.
What I would check before accepting an offer
My first check would be the total repayment rather than the amount deposited. A small advance can become expensive if fees or other charges are added, and the only figure that matters to the household budget is what must ultimately be repaid. I would write that number down and compare it with the money expected to remain after rent, utilities, food, transport and existing commitments.
Next, I would check the due date and the consequences of paying late. A household can afford a repayment in theory but still struggle if it arrives before wages or benefits. If the timing is unclear, I would not proceed until it is clear. The speed of the application should never pressure a borrower into accepting terms they cannot explain to the person sharing the budget.
I would also look at whether the proposed borrowing solves a one-off problem or simply postpones it. For a necessary repair with a confirmed incoming payment, a short-term option might be reasonable if the total cost is manageable. For recurring bills, medical costs without a repayment plan or existing loan payments, the better choice may be a different form of help. A bank overdraft, employer advance, credit-union product or negotiated payment arrangement may be slower, but could fit the situation more safely.
Another non-obvious tip is to prepare the household budget before opening the app, not after seeing an approval screen. Urgency can make a person anchor on the amount offered instead of the amount needed. If the repair costs less than the available advance, borrowing only what is necessary is generally easier to manage than taking extra money simply because it appears available.
I would keep records of the final agreement and repayment schedule in a private place. On a shared device, that might mean a secure personal note or paper record rather than an exposed screenshot. The record should include the amount, the due date and the total cost, but it should not be shared casually. This helps the borrower coordinate with a partner without distributing sensitive account information.
Where this app is stronger than familiar alternatives, and where it is weaker
Compared with visiting a bank branch, Fundi is more convenient for someone who wants to begin from a phone and investigate a cash advance outside normal office routines. Compared with asking friends or relatives, it offers a more formal route that does not depend on a personal conversation about lending. That convenience is the main reason I can see for choosing it when time matters.
However, convenience is not the same as value. A bank or credit union may offer clearer ongoing support, established account history and products designed for longer-term borrowing. An employer advance may avoid some of the uncertainty associated with a new lender, while a negotiated bill extension may be cheaper than borrowing at all. I would compare those options before treating Fundi as the default answer.
Traditional budgeting apps are also different. They help a household understand spending and plan ahead; Fundi is oriented toward borrowing money. If the real problem is that a family cannot see where its income goes, another loan app will not fix that. I would use a budgeting method alongside any borrowing decision, even if that method is only a simple written list.
The app’s public rating and install reach make it easier to consider than an unknown application, but popularity should not replace scrutiny. Reviews can tell me that many people have engaged with the product, yet they cannot decide whether a particular repayment schedule fits my income. I would pay more attention to the actual terms shown during my own application than to a general impression created by the rating.
Who should use it, and who should look elsewhere
I can see Fundi working best for an adult who has a specific, short-lived cash gap, understands the repayment source and is willing to read the complete terms before accepting anything. It may also be useful for comparing a quick digital borrowing route with more familiar alternatives, provided the user treats the first screen as an investigation rather than a commitment.
I would advise skipping it if the borrower is underage, applying on behalf of someone else, using a shared phone without clear privacy boundaries or hoping that a new advance will cover an existing pattern of debt. I would also look elsewhere if the household cannot identify the exact date and source of repayment. In those situations, speed can make the financial pressure worse.
People who need a larger, longer-term loan may be better served by a lender that offers detailed human support and a structured repayment product. Someone dealing with an emergency bill should first ask whether the provider can extend the deadline or accept installments. And anyone who feels rushed, confused or unable to calculate the total cost should stop rather than rely on the app’s promise of fast approval.
My household verdict
Borrow Money Instantly - Fundi is a focused finance app for adults exploring an urgent cash advance, and its free access, broad Android compatibility and strong public rating make it easy to try. I appreciate that it can put the borrowing process within reach of someone who does not want to visit a branch. At the same time, the app’s convenience is exactly why I would use it with firm boundaries.
For shared households, my recommendation is to keep the borrower’s identity, device access and repayment responsibility clear. Discuss the decision before applying, never treat an Everyone rating as permission for children to use the service, and do not confuse a fast response with an affordable loan. I would choose Fundi only after comparing the total repayment with a bank, credit union, employer option or bill arrangement.
My final view is cautiously positive rather than enthusiastic. Fundi may be a practical starting point for a well-defined short-term need, but it is not a replacement for budgeting, household communication or careful reading. If you can explain why you need the money, how much you need and exactly how you will repay it, the app may deserve consideration. If any of those answers are uncertain, a slower and more personal alternative is probably the wiser choice.
Pros
- Quick and easy loan approval process.
- User-friendly interface for all ages.
- No hidden fees or extra charges.
- Low-interest rates compared to competitors.,24/7 customer support available.
Cons
- Limited to specific regions or countries.
- Requires stable internet connection.
- May impact your credit score.
- Strict eligibility criteria for applicants.
- App contains frequent ads.
FAQs for Borrow Money Instantly - Fundi
What is Borrow Money Instantly - Fundi and how does it work?
Borrow Money Instantly - Fundi is a mobile application designed to provide quick and easy access to short-term loans. Users can apply for loans directly through the app, receive approval within minutes, and have funds transferred to their bank account. The app leverages technology to streamline the borrowing process, ensuring convenience and speed.
What are the eligibility requirements for borrowing money through Fundi?
To be eligible for a loan with Fundi, users must be at least 18 years old, have a valid government-issued ID, and maintain a stable source of income. The app may also require access to certain phone data to verify user identity and creditworthiness. Meeting these requirements enhances the chance of loan approval.
How does Fundi ensure the security of my personal information?
Fundi employs advanced encryption technologies and adheres to strict privacy policies to protect user data. The app ensures that personal and financial information is securely stored and only used for the purposes of loan processing. Users can feel confident that their privacy and security are top priorities.
What interest rates and fees should I expect when using Fundi?
Interest rates and fees for Fundi loans vary based on the loan amount, duration, and user credit profile. The app provides transparent information about all costs associated with borrowing, allowing users to make informed decisions. It is recommended to review all terms and conditions before accepting any loan offer.
Can I repay my Fundi loan early, and are there any penalties for doing so?
Yes, users can repay their Fundi loans early without incurring any penalties. Early repayment can help reduce the overall interest cost. The app offers flexible repayment options to accommodate the financial situation of each user, making it convenient to manage and settle the loan efficiently.











